State of Home Equity: West Market Briefing
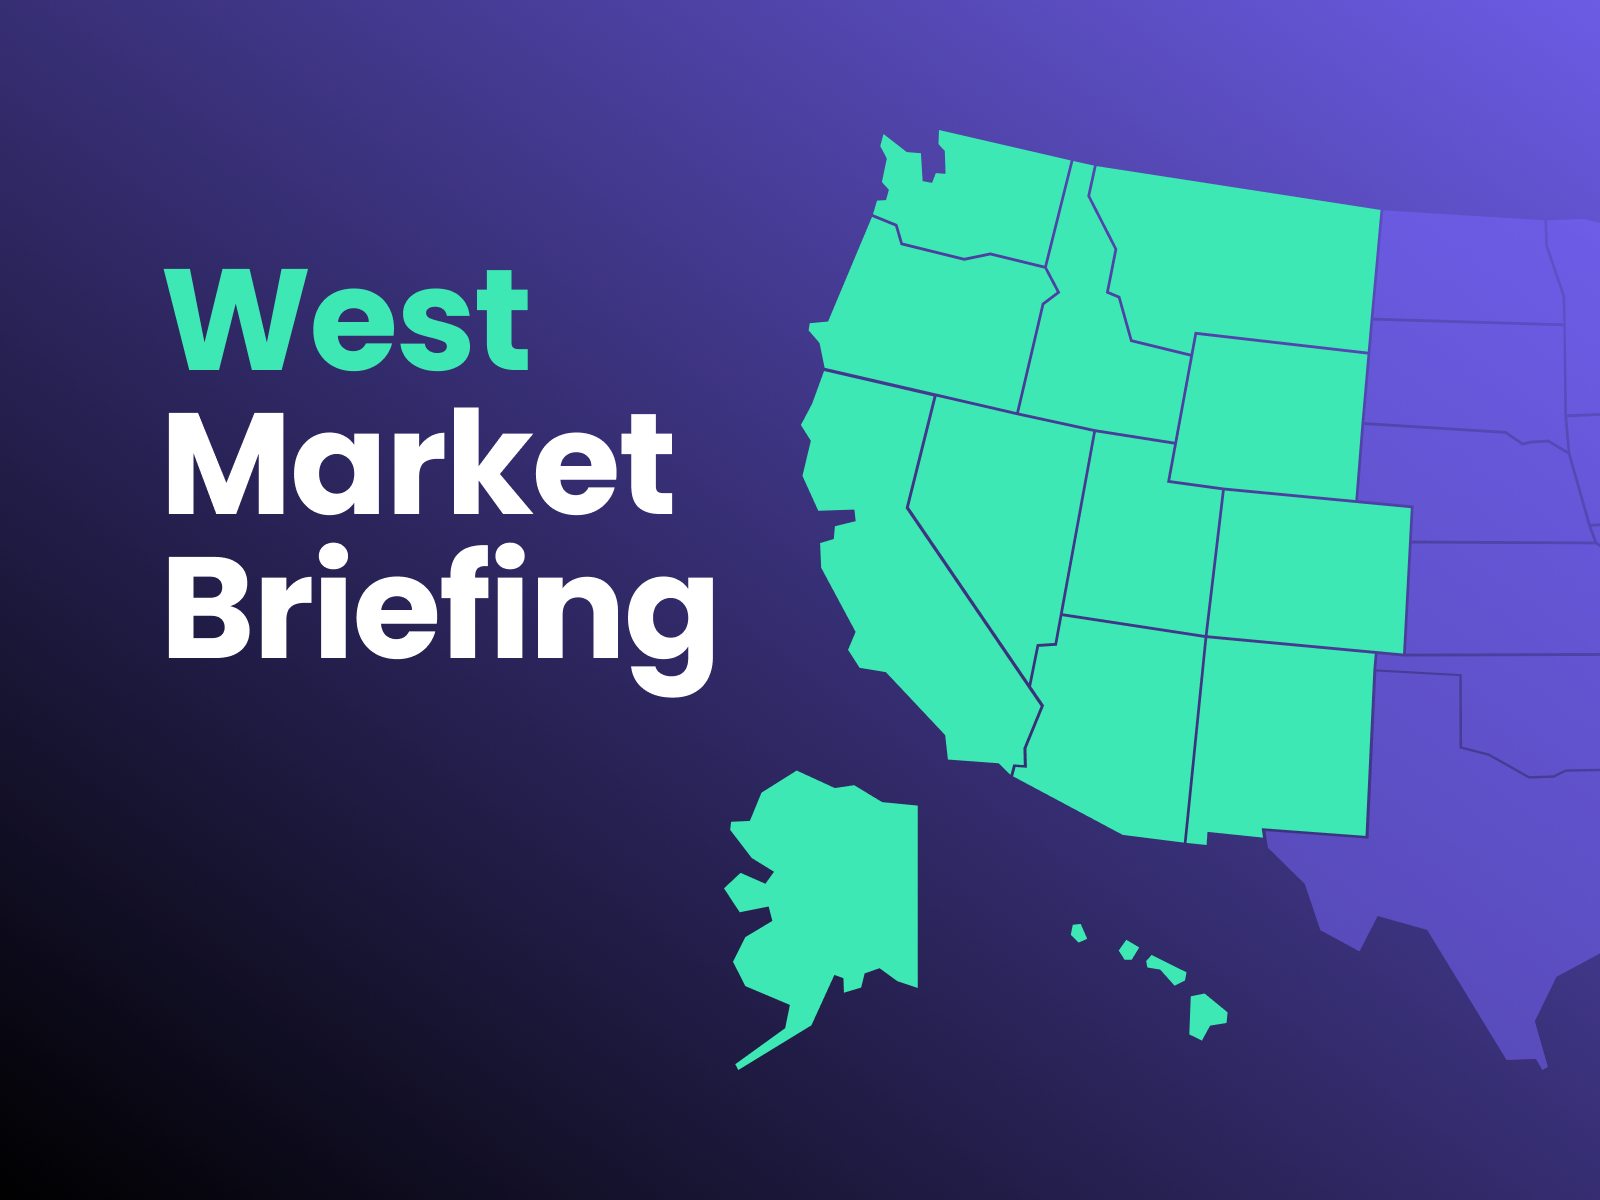
Watch our Market Briefing for the West on the market dynamics shaping home equity lending.


The West is home to some of the country’s highest home equity levels, but that doesn’t mean every market presents the same home equity opportunity.
Across the region, strong equity and borrower fundamentals are often paired with higher debt levels, very different geographic realities, and competitive environments that range from crowded markets to states where non-bank lenders dominate home equity visibility.
In this 30-minute briefing, we break down the factors shaping home equity opportunities in the West, and what this means for community lenders, including:
- Why high equity is only one part of the opportunity—and how borrower debt, market size, and competition change the picture from state to state
- Why higher homeowner debt may create a relevant debt-consolidation opportunity for the right borrowers
- How lenders can make large equity positions more tangible
- Why digital access plays two different roles across the West
- How lenders can respond to four different competitive environments
Watch the West Market Briefing →
Three growth models for the West
The data points to three different ways community lenders may approach home equity growth across the region.
Scale & Experience
California, Washington, Colorado, Oregon, & Arizona
These states combine meaningful homeowner scale with relatively active home equity markets and both digital & physical competition. Growth will depend on more than simply generating demand, lenders need enough visibility to enter the borrower’s consideration set, operational capacity to support that interest, and a borrower experience that makes it easy to move from consideration to funding. The opportunity is to pair reach with an experience that can convert demand efficiently.
Equity Activation
Hawaii, Montana, Idaho, & Utah
These states stand out for strong underlying homeowner equity. In these markets, the opportunity is about helping homeowners recognize what they already have. Community lenders can make equity tangible, connect it to relevant financial needs, and provide an easy way to explore available options. In Idaho and Montana especially, where non-banks dominate measured home equity visibility, proactive outreach can also help community lenders reclaim more of the borrower conversation.
Precision & Reach
Nevada, New Mexico, Wyoming, & Alaska
These states present more targeted opportunities shaped by borrower conditions, market size, and geography. Broad acquisition may be less effective here than identifying the homeowners who best fit the institution’s program and giving them a clear, accessible path forward. For geographically dispersed markets such as Wyoming and Alaska, digital capability can also extend the institution’s relationship beyond the physical branch, making it easier to capture opportunity across a wider footprint.
The West is equity-rich, but the state-level story matters.
Market-informed lending means looking beyond the regional average to understand what kind of opportunity exists in your footprint and aligning your marketing strategy, lending experience, and operating model around those insights.
Explore the full State of Home Equity report to see Market Potential, Borrower Quality, and Competitive Intensity for your state: